Steps to Define Personal Financial Priorities Effectively
Managing money effectively is not just about earning more—it’s about making intentional decisions with what you already have. One of the most important steps toward financial success is defining your personal financial priorities. Without clear priorities, it’s easy to spend impulsively, lose focus, and delay long-term goals.
When you understand what truly matters to you financially, every decision becomes easier. You gain clarity, reduce stress, and create a structured path toward a more secure future.
In this article, you’ll learn practical steps to define your financial priorities effectively and align your money with your goals.
1. Understand Your Current Financial Reality
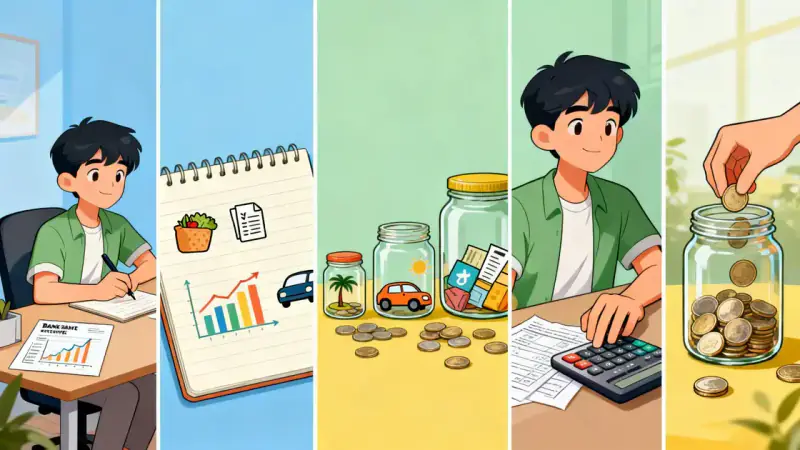
Before setting priorities, you need a clear understanding of your current financial situation. This means knowing exactly how much you earn, spend, save, and owe.
Start by listing:
- Your total monthly income
- Fixed expenses (rent, bills, subscriptions)
- Variable expenses (food, entertainment, shopping)
- Outstanding debts
- Current savings and investments
This financial snapshot helps you identify where your money is going and where adjustments may be needed.
2. Identify What Truly Matters to You
Financial priorities are deeply personal. What matters to one person may not matter to another.
Take time to reflect on your values and life goals. Ask yourself questions like:
- Do I value security or flexibility more?
- What are my short-term and long-term goals?
- What kind of lifestyle do I want to maintain?
Your answers will guide your financial decisions and help you focus on what truly matters.
3. Separate Needs from Wants
A critical step in defining financial priorities is distinguishing between needs and wants.
Needs are essential expenses required for living, such as housing, food, healthcare, and transportation. Wants are non-essential items like dining out, entertainment, or luxury purchases.
This distinction allows you to allocate your resources more effectively. While it’s important to enjoy your money, prioritizing needs ensures financial stability.
4. Set Clear and Measurable Goals
Once you understand your values, it’s time to translate them into specific financial goals.
Instead of vague goals like “save more money,” define clear objectives such as:
- Save $5,000 for an emergency fund within 12 months
- Pay off credit card debt in 18 months
- Invest 15% of your income for retirement
Clear goals make it easier to track progress and stay motivated.
5. Rank Your Financial Priorities
Not all financial goals are equally urgent. Some require immediate attention, while others can be planned over time.
Organize your priorities into categories:
- High priority: essentials, emergency fund, high-interest debt
- Medium priority: savings goals, education, moderate debt
- Low priority: lifestyle upgrades, luxury purchases
This ranking helps you focus your resources where they are needed most.
6. Create a Spending Plan That Reflects Your Priorities
Your spending habits should align with your financial priorities. This is where a well-structured budget becomes essential.
Allocate your income based on your ranked priorities. Ensure that essential expenses and savings come first, followed by discretionary spending.
A purposeful spending plan ensures that your money is working toward your goals instead of drifting aimlessly.
7. Build an Emergency Fund First
Before focusing on long-term goals, it’s important to establish a financial safety net.
An emergency fund should cover three to six months of living expenses. This protects you from unexpected situations such as job loss, medical emergencies, or urgent repairs.
Having this fund in place prevents you from going into debt and keeps your financial plan on track.
8. Address High-Interest Debt Quickly
Debt, especially high-interest debt, can hinder your financial progress. That’s why it should be a top priority.
Focus on paying off debts with the highest interest rates first. This reduces the overall cost and frees up more money for other goals.
As you eliminate debt, you create more room in your budget for saving and investing.
9. Plan for the Future with Investments
Once you’ve covered essentials and reduced debt, it’s time to think about long-term growth.
Investing allows your money to grow over time and helps you achieve goals like retirement or financial independence.
Start early, invest consistently, and focus on long-term strategies. Even small contributions can grow significantly over time.
10. Be Flexible and Adapt to Changes
Your financial priorities are not fixed—they will evolve as your life changes.
Major life events such as a new job, marriage, children, or relocation can shift your priorities. It’s important to revisit and adjust your plan regularly.
Flexibility ensures that your financial strategy remains relevant and effective.
11. Avoid Comparison with Others
One of the biggest obstacles to defining personal financial priorities is comparing yourself to others.
Everyone has different goals, incomes, and circumstances. What works for someone else may not work for you.
Focus on your own journey and make decisions based on your values and needs, not external pressure.
12. Track Progress and Celebrate Milestones
Tracking your progress keeps you motivated and accountable. Regularly review your financial goals and measure how far you’ve come.
Celebrate milestones along the way, whether it’s paying off a debt, reaching a savings target, or making your first investment.
These achievements reinforce positive habits and keep you focused on your long-term vision.
Aligning Your Money with What Matters Most
Defining your financial priorities is one of the most empowering steps you can take. It allows you to take control of your money and use it as a tool to build the life you want.
By understanding your current situation, setting clear goals, and aligning your spending with your values, you create a strong financial foundation.
Remember, financial success is not about perfection—it’s about consistency and intentionality. With the right priorities in place, every financial decision becomes a step toward a more secure and fulfilling future.