Lenders aim to reduce risk when providing funds. Because loans involve trust and financial responsibility, institutions analyze an applicant’s financial profile carefully. This process allows them to estimate whether the borrower will be able to repay the loan according to the agreed schedule.
By learning the key factors that influence loan approval, borrowers can make informed financial decisions and strengthen their financial profiles over time. This article explores the most common elements lenders evaluate and explains how they can affect the approval process.
Income Stability and Employment History
One of the most important elements lenders review is income stability. A reliable income source helps demonstrate that a borrower has the ability to make regular loan payments. Financial institutions often prefer applicants who show consistent earnings over time.
Employment history can also provide valuable insight. Long-term employment with a steady income may indicate financial reliability. On the other hand, frequent job changes or irregular income patterns may require additional documentation or explanation.
This does not mean individuals with varying income sources cannot qualify for loans. However, lenders may look more closely at overall financial stability to determine whether repayment will be manageable.
Credit History and Financial Behavior
Credit history plays a major role in the loan approval process. It provides lenders with a record of how an individual has managed borrowed money in the past. Payment behavior, existing credit accounts, and previous borrowing experiences help lenders evaluate risk.
Applicants who have consistently paid bills on time and maintained responsible credit usage are often viewed more favorably. Positive credit behavior demonstrates reliability and financial discipline.
If credit history includes missed payments or high debt levels, lenders may become more cautious. In some cases, additional verification or different loan terms may apply to account for the perceived risk.
Debt-to-Income Ratio
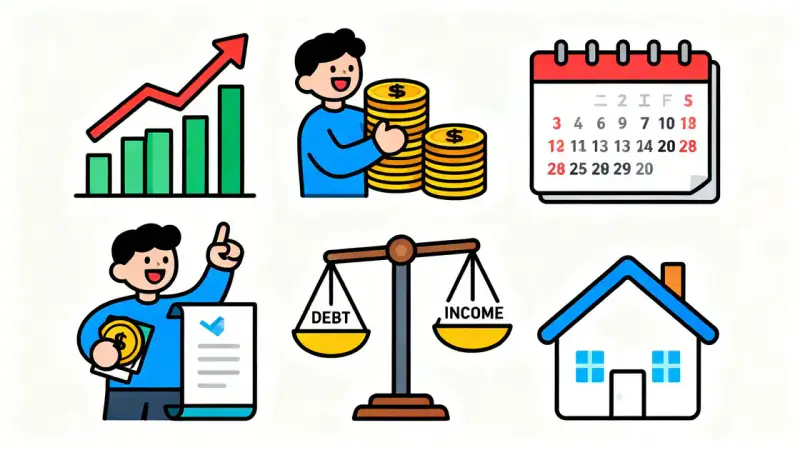
The debt-to-income ratio is another key factor lenders consider. This measure compares an applicant’s total monthly debt obligations to their monthly income. It helps lenders understand how much of a borrower’s income is already committed to existing payments.
If a large portion of income is used to cover existing debts, lenders may view the situation as financially stretched. This can reduce the likelihood of loan approval or result in smaller loan offers.
Maintaining a balanced debt-to-income ratio shows that a borrower has enough financial capacity to manage additional loan payments without excessive strain.
Loan Amount and Purpose
The specific loan request also influences approval decisions. Lenders typically evaluate the amount being requested and the purpose of the loan. Some loan types may involve different levels of risk depending on how the funds will be used.
For example, loans tied to assets or investments may be evaluated differently than unsecured personal loans. The requested amount also needs to align with the borrower’s financial capacity and repayment ability.
Providing clear information about the purpose of the loan can help lenders understand the context of the application and evaluate the request more accurately.
Credit Utilization and Existing Balances
Credit utilization refers to how much of a borrower’s available credit is currently being used. High utilization levels may signal financial pressure or reliance on credit, which can raise concerns for lenders.
Borrowers who maintain moderate credit usage often demonstrate better financial balance. Lower utilization suggests that credit is being used responsibly rather than excessively.
Keeping credit balances under control can therefore contribute positively to a borrower’s overall financial profile during the loan evaluation process.
Length of Credit History
The length of a borrower’s credit history also plays a role in loan approval decisions. Longer credit histories provide lenders with more information about financial behavior over time.
A well-established credit record allows lenders to see patterns of responsible borrowing and repayment. In contrast, individuals with very limited credit histories may present a challenge for lenders because there is less data available for evaluation.
This does not necessarily prevent loan approval, but it may lead to additional checks or slightly stricter conditions until more credit history is established.
Collateral and Secured Loans
Some loans require collateral, which is an asset used as security for the borrowed funds. Examples of collateral can include property, vehicles, or other valuable assets. When collateral is involved, lenders may feel more comfortable approving the loan because the asset reduces financial risk.
Secured loans often come with different approval criteria compared to unsecured loans. Because collateral provides an additional layer of protection, lenders may offer more favorable terms in certain cases.
However, borrowers should carefully understand the responsibilities associated with secured loans. If repayment obligations are not met, the lender may have the right to claim the pledged asset.
Application Accuracy and Documentation
The accuracy of the information provided in a loan application is another important factor. Lenders typically verify the details submitted by applicants, including income, employment, identification, and financial records.
Incomplete or inconsistent information can slow the approval process or lead to additional verification requests. Providing clear and accurate documentation helps lenders evaluate the application more efficiently.
Preparing necessary documents in advance, such as income statements or proof of employment, can make the process smoother and reduce delays.
Economic and Market Conditions
External economic factors may also influence loan approval decisions. Financial institutions operate within broader economic environments that affect lending policies and risk tolerance.
During periods of economic uncertainty, lenders may adopt stricter evaluation standards. In more stable economic conditions, lending criteria may be more flexible. These shifts can affect the availability of loans and the terms offered to borrowers.
Although individuals cannot control market conditions, maintaining strong personal financial habits can help strengthen their position regardless of broader trends.
Preparing for a Stronger Loan Application
Understanding the factors that influence loan approval can help borrowers approach the process with greater confidence. By focusing on financial stability, responsible credit behavior, and accurate documentation, applicants can improve their financial profiles over time.
Building a solid financial reputation is not something that happens overnight. It develops gradually through consistent financial decisions, responsible borrowing, and careful management of income and expenses.
Before applying for a loan, it may be helpful to review personal finances, evaluate current obligations, and ensure that the requested loan aligns with long-term financial goals.
Building Financial Confidence Over Time
Loan approval decisions are based on a combination of factors rather than a single element. Income stability, credit behavior, existing debts, and financial history all contribute to the overall evaluation process.
By understanding these key insights, individuals can make better financial choices and strengthen their financial standing over time. Responsible financial habits not only improve borrowing opportunities but also contribute to long-term financial stability.
Ultimately, knowledge and preparation play a major role in navigating the borrowing process successfully. With a clear understanding of what lenders evaluate, borrowers can approach financial opportunities with greater awareness and confidence.