When your dreams rest on the outcome, understanding the loan application requirements can make the difference between a life-changing “yes” and a disappointing “no.” Whether you are seeking funds for a new home, starting a business, or consolidating debt, knowing precisely what lenders look for will empower you to approach the process with confidence and clarity.
This detailed guide inspires, informs, and walks you through every critical step. Read on to equip yourself with the practical knowledge you need to turn your loan application into a resounding success.
The Power of Preparation: Why Requirements Matter
It’s easy to underestimate just how meticulous lenders can be. Every requirement they ask for serves as a checkpoint in their decision-making process. Meeting—and understanding—the full spectrum of lender expectations doesn’t just enhance your odds of approval; it ensures your application sails smoothly and swiftly through each review stage.
A well-prepared application eliminates many common points of delay or rejection. Think of it as your foundation for building credibility and trust with your potential lender.
Typical Loan Application Requirements You’ll Encounter
Let’s break down the most common requirements you’re likely to face when applying for a loan. While loan types may differ, some basic elements appear on almost every lender’s checklist:
- Valid identification documents: Such as a driver’s license or passport.
- Proof of income: Pay stubs, bank statements, or tax returns.
- Credit score and credit history reports.
- Employment verification: Employer contact details or recent pay statements.
- Personal and contact information.
- Debt-to-income ratio documentation.
- Purpose for the loan or use of funds.
Keep in mind that higher loan amounts or specific loan types (like mortgages or business loans) may require more detailed documents, such as property appraisals, business plans, or asset lists.
Why Lenders Insist on Documentation
Every document you’re asked to provide tells a story. Lenders want assurance that a borrower is both willing and able to repay the loan. Your documentation helps them verify financial stability and responsible behavior, mitigate risks, and comply with regulatory standards.
It’s normal to feel overwhelmed by the paperwork, but remember—each form, statement, or ID you submit closes the gap between where you are and where you want to be. Preparation is not just about fulfilling requirements; it’s about proudly presenting your readiness for financial opportunity.
The Hidden Factors: What Lenders Assess Beyond Paperwork
Some key requirements are less tangible but equally significant. Even after you’ve handed in every document, lenders weigh:
- Consistency in your financial history: Sudden spikes or dips in income may raise questions.
- Your employment stability and job type.
- Your level of existing debt and repayment patterns.
- The credibility of your references or cosigners (if applicable).
Understanding these deeper assessment criteria gives you a chance to address issues proactively or select the right moment to apply.
Building a Strong Application: Step-by-Step Practical Guidance
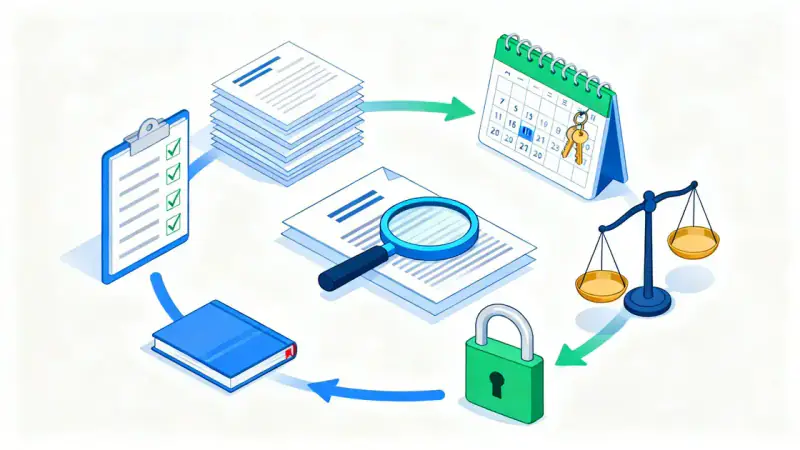
Each loan is unique, but there are universal steps you can take to strengthen your application, regardless of your goals or financial background:
- Organize all necessary paperwork before starting your application to avoid delays.
- Review your credit report for errors weeks before you apply. Correcting mistakes early can boost your chances.
- Prepare a brief, accurate explanation for any unusual activity or gaps in your financial history.
- Demonstrate stability—long-term employment and residence at the same address.
- Reduce existing debts where possible; a lower debt-to-income ratio improves approval odds.
Consider speaking openly with a loan officer before submitting if you have concerns—transparency often works in your favor and demonstrates responsibility.
Common Pitfalls (And How to Sidestep Them)
Even well-prepared applicants stumble over avoidable mistakes. Here’s how to stay ahead of the game:
- Never submit incomplete or conflicting information. Double-check every entry.
- Refrain from taking on new credit obligations right before applying.
- Don’t guess about your income or financial data—always use verified numbers.
- Avoid hiding past credit problems; honesty backed by proof of improvement is more persuasive.
Comparing Requirements Across Loan Types
Not all loans are created equal. The requirements for a credit card or a personal loan may differ from the hoops you must jump through for a mortgage or a business line of credit. Below is a table highlighting key differences in documentation needs for popular loan types:
| Loan Type | Key Documentation | Unique Requirements |
|---|---|---|
| Personal Loan | ID, proof of income, credit report | Reason for the loan |
| Mortgage | ID, income, tax returns, property info | Property appraisal, insurance verification |
| Auto Loan | ID, income, vehicle info | Car title, insurance documentation |
| Business Loan | ID, business plan, financial statements | Detailed business analysis, collateral proof |
Use this table as a reference to anticipate what you’ll need so you can move through the process seamlessly.
A Message of Motivation: Your Moment Awaits
Standing at the threshold of new possibilities, armed with knowledge about what lenders truly want to see, your journey to loan approval becomes less intimidating and more attainable. Each requirement you fulfill brings you closer to your next great chapter—whether it’s a new home, thriving business, or consolidated peace of mind.
Remember: Behind every approval is a story of preparation, diligence, and hope. By mastering the art of the loan application process from start to finish, you not only unlock funds—you unlock future opportunities and the power to shape your own financial destiny.
Your best chance of success is within reach. Gather your documents, strengthen your finances, and take confident steps toward realizing your dreams. The only thing left is to begin.