Family Financial Planning Guide: Master Your Future Today
Family financial planning plays an essential role in building long-term stability and security. Managing money as a family involves more than simply paying bills each month. It requires thoughtful planning, shared goals, and responsible financial habits that support both present needs and future aspirations.
Families face a wide range of financial responsibilities, including housing, education, healthcare, transportation, and daily living expenses. Without a clear plan, these responsibilities can quickly become overwhelming. However, with a structured financial strategy, families can manage resources more effectively and prepare for important life milestones.
This guide explores key principles of family financial planning and offers practical strategies to help families organize their finances and work toward a more secure future.
Why Family Financial Planning Matters
Financial planning helps families make informed decisions about spending, saving, and long-term goals. When finances are organized and transparent, families are better prepared to handle both expected expenses and unexpected situations.
One of the main benefits of family financial planning is reducing financial stress. Clear financial plans help prevent misunderstandings about money and encourage responsible financial behavior among all members of the household.
Additionally, financial planning allows families to prioritize what matters most, whether it is education, home ownership, travel, retirement preparation, or building a financial safety net.
Establish Shared Financial Goals
Successful family financial planning begins with setting shared financial goals. These goals provide direction and help guide financial decisions. When all family members understand the purpose behind financial choices, it becomes easier to stay committed to the plan.
Family goals may include saving for a home, preparing for children’s education, paying off debt, building an emergency fund, or planning for retirement. Some goals may be short-term, while others may extend over many years.
Open discussions about financial priorities help ensure that everyone’s expectations are considered and aligned.
Create a Family Budget
A family budget is one of the most important tools for managing household finances. It helps track income, organize expenses, and ensure that money is allocated effectively.
To create a family budget, start by identifying all sources of income. Then list essential expenses such as housing, utilities, groceries, transportation, insurance, and childcare. After accounting for these necessities, families can allocate funds for savings, investments, and discretionary spending.
Regularly reviewing the budget helps ensure that spending remains aligned with family goals and financial priorities.
Build a Strong Emergency Fund
An emergency fund provides financial protection during unexpected situations. Job loss, medical expenses, home repairs, or vehicle breakdowns can create financial pressure if families are not prepared.
Setting aside money in a dedicated emergency fund allows families to manage unexpected costs without relying on high-interest credit or loans. Even small contributions made consistently can gradually build a reliable financial cushion.
A strong emergency fund helps families maintain financial stability during uncertain times.
Manage Debt Responsibly
Debt management is an important part of family financial planning. While certain types of borrowing may be necessary for major life events such as home purchases or education, excessive debt can limit financial flexibility.
Families benefit from creating a strategy to manage existing debt effectively. This may involve prioritizing higher-interest balances, maintaining consistent payments, and avoiding unnecessary borrowing.
Reducing debt over time allows families to redirect more money toward savings, investments, and future goals.
Plan for Children’s Future Needs
For many families, preparing for children’s future needs is a major financial priority. Education costs, extracurricular activities, and other developmental opportunities can represent significant expenses over time.
Planning ahead helps families distribute these costs gradually rather than facing large financial burdens later. Setting aside savings specifically for education or future opportunities can provide valuable support when the time comes.
Financial planning also provides an opportunity to teach children basic financial principles such as saving, budgeting, and responsible spending.
Protect Your Family With Insurance
Insurance plays a critical role in protecting family finances from unexpected events. Health insurance, life insurance, disability coverage, and property protection can help reduce financial risks that could otherwise disrupt a family’s stability.
Each family’s insurance needs may vary depending on factors such as income, dependents, employment benefits, and lifestyle. Reviewing coverage regularly ensures that protection remains adequate as circumstances change.
Insurance does not eliminate risk, but it can help reduce the financial impact of unexpected challenges.
Plan for Long-Term Financial Security
Long-term planning is a vital component of family financial health. While immediate expenses often demand attention, planning for the future ensures that families remain financially stable in later years.
Saving for retirement, investing for long-term growth, and maintaining financial discipline are important steps toward achieving long-term security. The earlier families begin planning for the future, the more time their savings and investments have to grow.
Consistent contributions and thoughtful financial decisions can help families build lasting financial stability.
Encourage Open Communication About Money
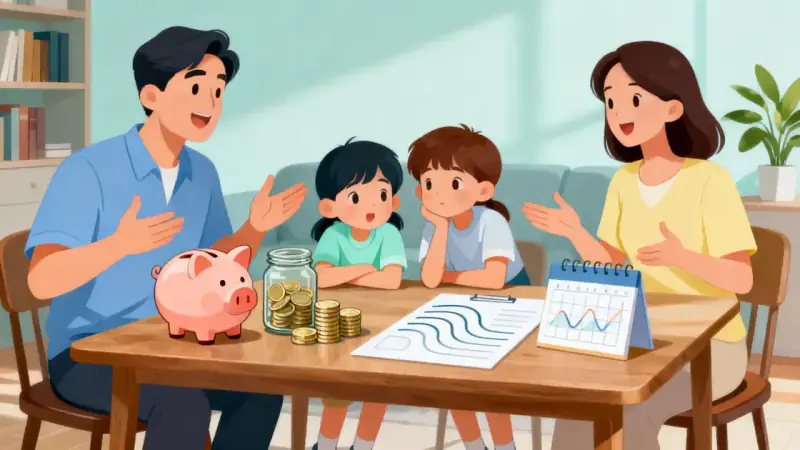
Open communication about finances helps families avoid misunderstandings and maintain transparency. When family members discuss financial decisions openly, they develop a better understanding of shared responsibilities and priorities.
Regular conversations about budgeting, spending, and financial goals encourage accountability and cooperation. These discussions also help children learn responsible financial habits that they can carry into adulthood.
A supportive and transparent environment strengthens both financial planning and family relationships.
Review and Adjust Financial Plans Regularly
Family financial plans should evolve as circumstances change. Changes in income, employment, family size, housing, or health may require adjustments to financial strategies.
Reviewing financial plans regularly helps families stay prepared and maintain progress toward their goals. Adjustments may involve updating budgets, increasing savings contributions, or revisiting long-term objectives.
Flexibility allows families to adapt their financial strategies while continuing to work toward a secure future.
Building a Strong Financial Future Together
Family financial planning is an ongoing process that requires cooperation, discipline, and thoughtful decision-making. By setting clear goals, creating a realistic budget, building savings, managing debt responsibly, and protecting against risks, families can strengthen their financial foundation.
Every family faces unique financial challenges and opportunities, but the principles of planning, communication, and consistency remain universal. When families work together toward shared financial goals, they build not only financial stability but also confidence in their future.
With careful planning and steady progress, families can create a financial strategy that supports both their present needs and their long-term aspirations.