Many people only think about credit history when they need to borrow money. However, credit history is something that develops gradually over time based on financial behavior. Lenders use this information to evaluate risk and determine the terms they are willing to offer. A strong credit history can open the door to more borrowing options, while a weak one may limit opportunities.
This article explains how credit history works, why lenders pay attention to it, and what borrowers can do to improve their financial reputation over time.
What Is Credit History?
Credit history is a record of how a person has managed borrowed money in the past. It includes information about loans, credit cards, payment behavior, and the length of time credit accounts have been active. Financial institutions use this history to understand whether someone has demonstrated responsible borrowing habits.
When individuals borrow money or use credit-based services, those activities are typically reported to credit bureaus. These organizations collect and maintain financial data related to borrowing behavior. Lenders then review this information when evaluating loan applications.
A person’s credit history may include details such as payment consistency, outstanding balances, types of credit accounts, and how long those accounts have been open. Together, these elements help create a financial profile that lenders use to assess potential borrowers.
Why Lenders Review Credit History
Financial institutions aim to reduce risk when providing loans or extending credit. Reviewing credit history helps lenders estimate the likelihood that a borrower will repay the money according to the agreed terms. Because lending involves financial risk, lenders rely on past behavior as a useful indicator.
If someone has consistently made payments on time and maintained responsible credit usage, lenders may view that person as a lower-risk borrower. On the other hand, missed payments, high debt levels, or a limited credit history may cause lenders to be more cautious.
This evaluation process helps lenders decide whether to approve an application, how much money they are willing to lend, and what interest rate or conditions should apply.
How Credit History Influences Borrowing Options
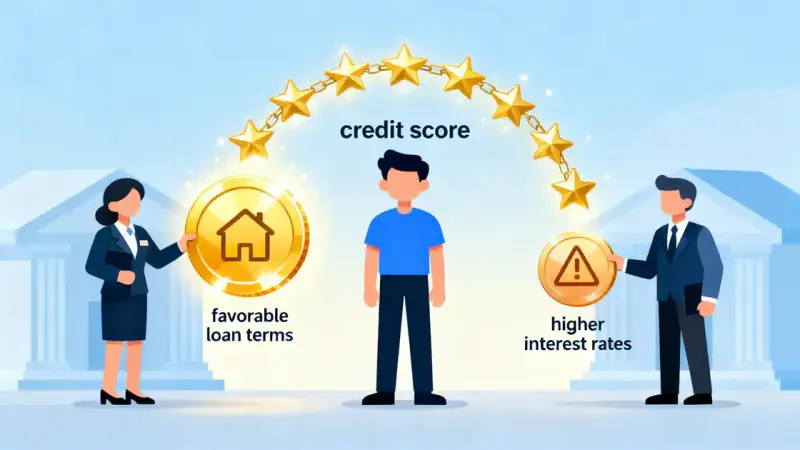
Credit history can influence several aspects of the borrowing process. One of the most noticeable effects is the variety of financial products available to a borrower. Individuals with strong credit histories typically have access to more lending options and competitive terms.
Borrowers with well-established credit records may qualify for loans with lower interest rates, higher borrowing limits, and more flexible repayment conditions. These benefits can significantly reduce the overall cost of borrowing.
In contrast, individuals with limited or weaker credit histories may face stricter conditions. Some lenders may require additional verification, offer smaller loan amounts, or charge higher interest rates to offset the perceived risk. In some cases, applications may be declined entirely.
Key Factors That Shape Your Credit History
Several factors contribute to the strength of a credit history. Understanding these elements can help individuals make financial decisions that support a healthier credit profile over time.
Payment consistency is one of the most important components. Paying bills on time demonstrates reliability and financial discipline. Late or missed payments can negatively affect a credit profile.
Credit utilization refers to how much credit someone uses compared to their available credit limit. Using a moderate portion of available credit often signals responsible borrowing behavior.
Length of credit history also matters. Accounts that have been active for longer periods provide lenders with more data about a borrower’s financial behavior.
Types of credit accounts can also play a role. A mix of credit products, such as installment loans and revolving credit accounts, may demonstrate experience managing different financial responsibilities.
How Credit History Can Affect Interest Rates
Interest rates are one of the most visible ways credit history affects borrowing. When lenders perceive lower risk, they may offer more favorable rates. Even small differences in interest rates can have a meaningful impact on the total cost of a loan over time.
For example, two borrowers applying for similar loans may receive different interest offers depending on their credit profiles. A borrower with strong credit history may qualify for a lower rate, which reduces the overall repayment amount.
On the other hand, borrowers with weaker credit histories may receive higher rates. This adjustment helps lenders compensate for the additional risk associated with lending.
Limited Credit History and Its Challenges
Some individuals face borrowing challenges not because of negative credit behavior, but because they have little or no credit history. This situation is common among young adults, newcomers to a financial system, or individuals who have rarely used credit products.
Without enough historical data, lenders may have difficulty evaluating financial reliability. As a result, these borrowers may initially face limited borrowing options or stricter conditions.
Building credit history gradually through responsible use of financial products can help address this challenge. Over time, consistent payment behavior provides lenders with the information they need to assess risk more confidently.
Steps to Build a Stronger Credit Profile
Improving credit history does not happen overnight, but steady financial habits can make a meaningful difference. Responsible credit use, combined with careful financial planning, helps strengthen a credit profile over time.
One of the most effective practices is paying bills consistently by their due dates. Payment reliability signals financial responsibility and helps build trust with lenders.
Maintaining manageable credit balances is also helpful. Using credit thoughtfully and avoiding excessive borrowing can contribute to a healthier financial record.
Monitoring credit reports periodically can help individuals identify inaccuracies or areas for improvement. Staying informed about one’s financial profile encourages better financial management.
Responsible Borrowing and Financial Awareness
Understanding how credit history affects borrowing options empowers individuals to make more thoughtful financial decisions. Rather than viewing credit only as a tool for borrowing, it can be helpful to see it as part of a broader financial reputation.
Responsible borrowing involves evaluating whether a loan is truly necessary, understanding repayment terms, and ensuring that new financial commitments fit comfortably within a personal budget.
Financial awareness also means recognizing that building a strong credit profile takes time. Patience, consistency, and responsible behavior are essential elements of long-term financial health.
Looking Ahead: Strengthening Your Financial Opportunities
Credit history plays an important role in shaping borrowing opportunities. Lenders rely on past financial behavior to evaluate risk, determine eligibility, and establish loan conditions. A well-managed credit history can provide access to more options and better financial terms.
By understanding how credit history works and developing responsible financial habits, individuals can gradually strengthen their credit profiles. Over time, these efforts can lead to improved financial flexibility and greater confidence when making borrowing decisions.
Building a positive credit history is not about perfection. It is about consistent, responsible financial behavior that supports long-term stability and opportunity.