Quick Loan Guide explains how quick loans offer a fast solution for urgent financial needs. By understanding quick loan options, borrowers can access funds swiftly and with more confidence.
In many situations, a Quick Loan Guide can help borrowers evaluate when these loans are useful. They are popular for emergencies or planned expenses, but it is important to carefully consider the benefits and risks.
Following a reliable Quick Loan Guide helps you make informed decisions and navigate the quick loan landscape with clarity and safety.
Understanding Quick Loans
Understanding quick loans is essential for anyone facing urgent financial needs. These loans are designed to provide fast cash with minimal documentation. Borrowers can access money quickly, helping them manage unexpected expenses.
Quick loans often come with easy applications and faster approval times. This process appeals to many individuals who require immediate funds for personal or emergency costs.
However, it’s important to approach quick loans with care. They can carry higher interest rates compared to traditional loans, which may lead to greater costs in the long run.
Types of Quick Loans
- Personal loans: Flexible loans that can be used for various expenses, often with fixed repayment terms.
- Payday loans: Short-term loans designed to cover immediate expenses until the next paycheck.
- Installment loans: Loans repaid over time through scheduled monthly payments.
- Online quick loans: Fast approvals offered by digital lenders with minimal paperwork.
- Credit line loans: Allow borrowers to access funds as needed up to a set limit.
How to Apply for a Quick Loan
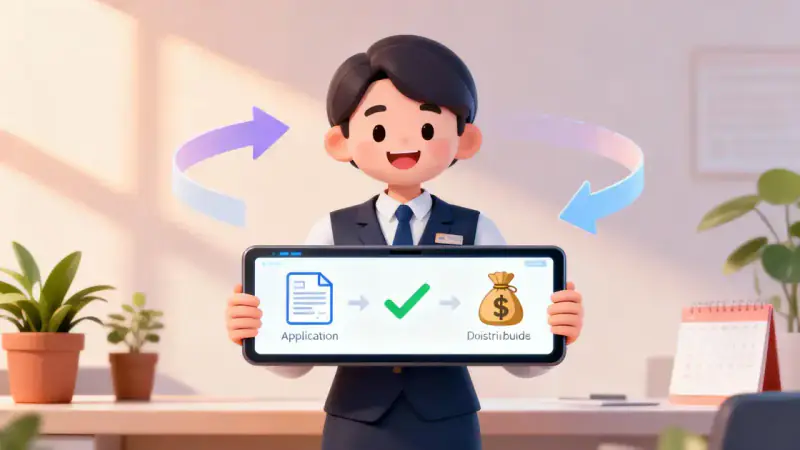
Applying for a quick loan can be straightforward if you know the right steps to follow. First, research different lenders to find the best rates and terms. Comparing options helps in making an informed choice.
Next, gather the necessary documents. Typically, you’ll need proof of income, identification, and bank information. Having these ready speeds up the application process.
Once you have everything, fill out the loan application form carefully. Review it before submission to avoid any mistakes that could delay processing.
Factors to Consider Before Borrowing
Before borrowing money, it is important to consider several factors to make smart financial choices. First, assess your current financial situation, including your income and expenses. This helps identify how much you can afford to borrow.
Next, understand the interest rates and fees associated with the loan. Higher rates can lead to significant costs over time. Make sure to read the loan agreement carefully.
Lastly, evaluate the repayment terms. Choose a loan with terms that fit your ability to pay back the borrowed amount comfortably.
Benefits of Quick Loans
Quick loans offer several benefits for those in urgent need of cash. One major advantage is that they provide fast access to funds, often within a day. This can be crucial during emergencies, such as medical expenses or car repairs.
Additionally, the application process for quick loans is usually simple and straightforward. Most lenders offer online applications, making it easy to apply from home.
However, quick loans also come with other benefits worth knowing about.
- Flexible loan amounts to meet various needs.
- Minimal documentation required for approval.
- No lengthy waiting periods for cash.
Risks Involved with Quick Loans
While quick loans can be helpful, they also come with risks that borrowers should understand. One major risk is high-interest rates. Many lenders charge significant fees, which can lead to paying back much more than the original amount borrowed.
Another concern is the potential for debt cycles. If borrowers cannot repay their loans on time, they might need to take out new loans to cover old ones. This can quickly spiral out of control.
Being aware of these risks helps individuals make wise borrowing decisions.
- High-interest rates can lead to larger debt.
- Short repayment periods may not fit all budgets.
- Risk of damaging credit scores if loans are unpaid.
Improving Your Loan Eligibility
Improving your loan eligibility is important for securing the funds you need. One key factor is maintaining a good credit score. Lenders often check this score to evaluate your borrowing risk.
You can also boost your eligibility by reducing existing debts. This will show lenders that you can manage your finances well.
Having a steady income source is another crucial element. A reliable paycheck makes you a more attractive borrower.
- Pay your bills on time to improve your credit score.
- Limit new credit applications before borrowing.
- Consider getting a co-signer to strengthen your application.
Tips for Responsible Borrowing
Responsible borrowing is crucial for maintaining financial health. Start by only borrowing what you truly need. This helps to avoid overwhelming debt that may be hard to repay.
Always read the loan terms carefully before signing. Understanding the interest rates and repayment schedule will make you a more informed borrower.
Finally, create a budget that includes your loan payments. Planning your monthly expenses ensures you won’t miss payments.